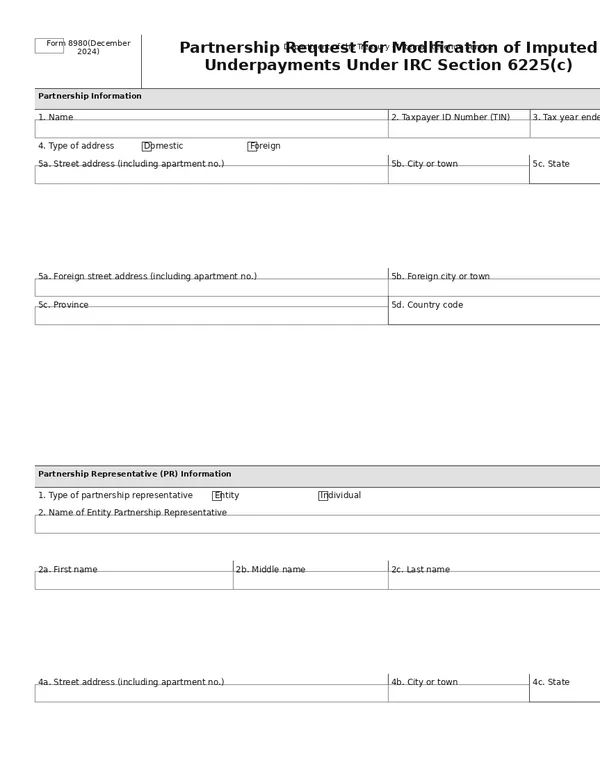
When to use Form 8980
An imputed underpayment is computed at the highest rate on net positive adjustments, regardless of who the partners are. Modification lets the partnership show that some of that tax would not actually be owed. Pub 5346 states Form 8980 “is submitted by a partnership to request the modification of an imputed underpayment under section 6225(c),” and that an IU “is reported to a partnership in a notice of proposed partnership adjustment (NOPPA).” See how the IU is computed and modification requests.
It is not a protest. Pub 5346: “A request for modification is a request to modify an imputed underpayment and is not a request to appeal or modify partnership adjustments.” Disputes over the adjustments go to Appeals by protest before the NOPPA (see BBA cases in Appeals).
Form 8980 is also attached to an AAR when the partnership applies permitted modifications to an IU it reports. Only some modifications work there: Pub 5346 lists tax-exempt partners, the applicable rate, certain PTP passive losses, grouping limits, qualified investment entity partners, treaty and statutory exemptions and other modifications, and says “Modifications for partner amended returns, partner alternative procedure, and closing agreements are not permitted in an AAR.”
Item by item
- HeaderPartnership Information; Partnership Representative (PR) Information
- Lines 1 to 5: name (no double spaces or punctuation), TIN, tax year ended and address, then the PR's information. Pub 5346 says each Form 8980 pertains to one partnership and one reviewed year.
- Item AModification(s) Submission Type
- Original (the first request for the year, and still Original if a prior submission was rejected), Supplemental (in addition to an accepted original), Corrected (replaces all prior accepted submissions), or Supporting Documents; and whether it is attached to an AAR.
- Item BModification(s) Requested
- Check each type requested; each box unlocks the matching Part of Item E.
- Item CSource Partnership Structure, Ownership, and Allocations of Adjustments Relevant to Modification
- Required. The structure table of tiers and partners relevant to the requested modifications, and allocation tables showing each relevant partner's share of each adjustment, whether positive or negative, its grouping and subgrouping, and whether it was in the general or a specific IU.
- Item DRequest for Modification Pre-Approval Relating to Partners of a Pass-Through Entity Partner
- Used to ask the IRS to pre-approve modifications based on indirect partners' actions, with the explanation the instructions require.
- Item E IAmended Returns of Partners and Partner Alternative Procedure, IRC 6225(c)(2)
- Number of relevant partners filing modification amended returns or using the alternative procedure; each partner signs Form 8982 with a signature file. Partner payments are identified as Partner Payment for BBA Modification.
- Item E IITax-Exempt Partners, IRC 6225(c)(3)
- Partners that are tax-exempt or foreign partners exempt under 501(a); Form 8983 certification for each.
- Item E IIIApplicable Highest Tax Rate, IRC 6225(c)(4)
- A lower rate for the portion of the IU allocable to C corporation partners, and to individual or S corporation partners for capital gain or qualified dividend adjustments (Pub 5346).
- Item E IVPassive Activity Losses of PTPs, IRC 6225(c)(5)
- Specified or qualified relevant partners; Form 15028 certification; IRS pre-approval required.
- Item E V to IXNumber and composition of IUs; QIE partners; partner closing agreements; treaty and statutory exemptions for foreign partners; other modifications
- Part V regroups adjustments and requests specific IUs; Part VII covers partner closing agreements; Part IX covers other modifications the IRS may allow.
- Item FSignature of Partnership Representative
- PIN signature by the PR; Pub 5346 says a POA for the PR may sign using the POA's PIN when the PR cannot.
Where and how to submit it
For a NOPPA, Pub 5346 says to upload the completed fillable form, not a printed and scanned copy, through the BBA electronic submission process (IRS.gov/bbaesubmit). Forms 8980, 8982, 8983 and 15028 must be submitted in fillable format; signature files and attachments can be scanned. Attachments must follow the naming rules: letters, numbers, hyphens and underscores, at most 50 characters, allowed extensions .doc, .docx, .pdf, .xls, .xlsx and .zip.
- Calendar the 270th day after the NOPPA mailing date, the IRC 6225(c)(7) deadline.
- Furnish each relevant partner its share of all NOPPA adjustments; Pub 5346 warns that failing to give partners the information they need can lead to denial.
- Collect partner amended returns and payments, Forms 8982 and 8983, and any treaty or rate documentation.
- If more time is needed, submit Form 8984 and get it approved before the 270 days end.
- Submit Form 8980 with all related forms; a submission meets the deadline only if it is in accepted status before the period expires.
- If nothing more is coming, consider Form 8981 to waive the rest of the period and move to the FPA.
For an AAR, attach Form 8980 to the AAR, which is filed where and how the original return was filed. Pub 5346: “If a modification is requested but the Form 8980 is not attached to the AAR, the modification is denied.”
What the IRS does with it
IRM 4.31.13.8 lists the nine modification types and restates the deadline: “Under IRC 6225(c)(7), a partnership has 270 calendar days from the mail date of the partnership's NOPPA to request modification.” The revenue agent performs due diligence to approve, partially approve or disallow each request, entering approvals in the IUA calculator. Requests received within 5 days of the deadline are worked as soon as possible; otherwise the pre-review is done within 3 business days.
The burden is on the partnership. Pub 5346 says the partnership “must demonstrate to the satisfaction of the IRS that any modification requested is appropriate and accurate,” and the IRS may deny modification if the evidence is insufficient.
The decision goes out on Letter 5975 with Form 15027 and Form 14726. IRM 4.31.13.8.2: “The PR has 10 days from the issuance date of Letter 5975 to respond.” Signing and returning Forms 15027 and 14726 waives the FPA and consents to assessment of the modified IU. If the PR disagrees, Pub 5346 says the partnership may first request a conference with the group manager and then appeal to the Independent Office of Appeals. With no response, the IRS proceeds to the FPA, after which the partnership pays the modified IU or elects push-out on Form 8988.
Modifications and push-out do not stack on an AAR. The Form 8082 instructions say that if the partnership makes a valid election to push out the AAR adjustments, any modifications applied on Form 8980 are disregarded.
Common mistakes
- Missing the 270-day window or asking for an extension after it has run.
- Item C incomplete. It is required, and allocation detail must back every adjustment relied on.
- Partners not given their NOPPA allocations, so their amended returns do not match.
- Scanned primary forms. Form 8980 must be uploaded in fillable format.
- Marking a resubmission as Corrected when the prior submission was rejected; it should still be Original.
- Using exam-only modifications on an AAR (amended returns, alternative procedure, closing agreements).
Questions practitioners ask
How long does a partnership have to file Form 8980?
270 calendar days from the date the NOPPA is mailed, under IRC 6225(c)(7). The period can be extended with Form 8984 if approved before it expires.
Is a modification request the same as appealing the audit?
No. Pub 5346 says it modifies the IU only, not the partnership adjustments. Disputes over the adjustments go to Appeals by protest before the NOPPA.
Can modifications be used on an AAR?
Some can. Pub 5346 says amended return, alternative procedure and closing agreement modifications are not permitted in an AAR, and a modification not supported by an attached Form 8980 is denied.
What happens after the IRS decides?
It sends Letter 5975 with Forms 15027 and 14726. The PR has 10 days to respond (IRM 4.31.13.8.2), may request a group manager conference and then Appeals, or may sign to waive the FPA and agree to the modified IU.
Can the PR end the modification period early?
Yes, with Form 8981, which IRM 4.31.13.8 says waives the remaining period; once accepted, no further modifications can be filed for that year.