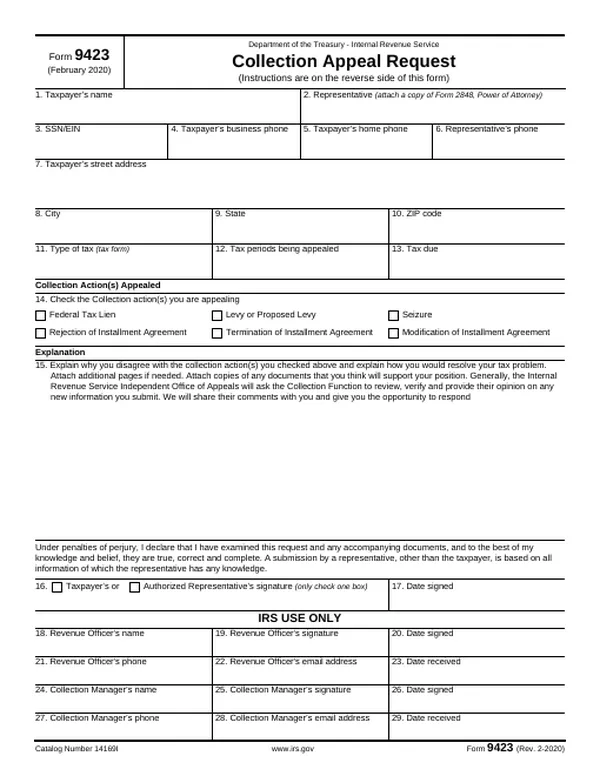
When to use Form 9423, and when another route is right
CAP is available to the taxpayer, or a third party whose property is subject to the action, for (IRM 5.1.9.4): a levy or seizure taken or proposed; an NFTL filed or proposed, including nominee and alter ego liens; denials of lien certificates (subordination, discharge, non-attachment) and of lien withdrawal requests; rejected, modified or terminated installment agreements and proposals to modify or terminate them; and disallowed claims for return of levied property under IRC 6343(b) and (d).
CAP is excluded for (IRM 5.1.9.4.1) trust fund recovery penalties, offer rejections, penalty appeals, most jeopardy levies, audit reconsideration, refund or abatement claims, original requests for return of levied property, and matters under court or Department of Justice control. It cannot be used to dispute the underlying liability or Collection's refusal to release a lien.
Compare CAP with CDP before filing. IRM 8.24.1.2 sums it up: under CAP, the Appeals decision is final and the goal is a five business day turnaround; under CDP, the determination can go to Tax Court, Appeals considers collection alternatives and liability challenges, and the collection statute is suspended. Appeals in CAP is narrow: “Appeals does NOT consider alternatives to the issue under appeal, but solely determines the appropriateness of the issue under appeal.” If a CDP notice was issued and the window is open, Form 12153 usually gives more. If both are requested on the same event, Appeals asks the taxpayer to choose, and if the taxpayer will not decide, gives the CDP hearing. More on the Collection Appeals Program.
Line by line
- 1, 3Taxpayer's name and SSN/EIN
- 2, 6Representative and phone
- Attach a copy of Form 2848. A representative can appear without the taxpayer only with a properly completed Form 2848.
- 4-5, 7-10Taxpayer's phones and address
- 11-13Type of tax, tax periods being appealed, tax due
- List the form numbers and every period the action affects.
- 14Collection action(s) appealed
- Federal Tax Lien, Levy or Proposed Levy, Seizure, Rejection of Installment Agreement, Termination of Installment Agreement, Modification of Installment Agreement. Lien certificate denials and return-of-property disallowances are also appealable under the instructions; describe them in block 15.
- 15Explanation
- Why the action is wrong and how the taxpayer would resolve the liability. Attach documents. If the manager did not call back within two business days, note the date of the conference request here and that no manager contacted the taxpayer. Appeals usually asks Collection to comment on new information and shares the comments.
- 16-17Signature and date
- Taxpayer or authorized representative (check one box), under penalties of perjury.
- 18-29IRS use only
- Revenue officer and collection manager names, signatures, contact details and dates received. Leave blank.
Where and how to file
Form 9423 goes to the Collection office that took the action, not to Appeals. The instructions say: “Never forward your request for an Appeals conference directly to Appeals.” The timelines differ by action:
| Action | Steps and deadlines (form instructions and IRM 5.1.9.4.2) |
|---|---|
| Lien or levy | Ask for a conference with the employee's manager. Tell Collection within 2 business days after the conference that Form 9423 is coming. “The Form 9423 must be received or postmarked within three (3) business days of the conference with the Collection manager or collection action may resume.” |
| Manager does not call back | If no manager or designee calls within 2 business days of the request, submit Form 9423 within 4 business days of the conference request, noting the missed callback in block 15. |
| Seizure | Appeal to the Collection manager within 10 business days after the Notice of Seizure (Form 2433) is given or left. |
| Installment agreement rejected, modified or terminated | Submit within 30 calendar days to the office or revenue officer that acted. A manager conference is recommended but not required. Levy is barred by statute during the 30 days and during a timely appeal. |
Outside those cases, “There is no deadline for requesting a CAP appeal in most situations”, but delay can make the appeal moot; once levy proceeds are turned over, the remedy becomes an administrative claim for return of property. IRM 5.1.9.4.2 also says a CAP request filed more than three business days after the conference loses the stay but can still be heard if received within a reasonable time, such as ten business days. On Automated Collection System cases, IRM 8.24.1.3.6 allows an oral CAP request after speaking with the ACS manager. Faxing the form at or right after the manager conference avoids the short mailing window.
What the IRS does with it
The revenue officer records the request on ICS, and the group manager must return the call within two business days. If the conference does not resolve it, Collection sends the case to Appeals within two business days with Form 15044, the Form 9423, the lien, levy or seizure documents, and any Form 433-A or 433-B. The transmittal must be neutral; any prohibited ex parte content must be shared with the taxpayer (IRM 5.1.9.4.3). Appeals returns premature referrals, such as a lien or levy appeal with no manager conference.
Appeals aims to finish quickly. IRM 5.1.9.4.4: “The Appeals organization tries to resolve CAP cases within five business days of the receipt of the case by the appeals officer”, and attempts a conference within two business days. Further levy is generally suspended during the appeal, but Collection can levy with manager concurrence if collection is at risk, the issues are frivolous, or the appeal is solely to delay. Further lien action is generally withheld unless needed to protect the government. The instructions add that collection is normally stopped unless the IRS believes collection or the amount owed is at risk.
The decision: “Decisions by Appeals are binding on the taxpayer and Collection.” Collection carries out what Appeals directs, but a later default releases Collection from the terms, and false or withheld information makes the agreement voidable. The same issue cannot be appealed again on the same facts. The instructions are clear that “You cannot obtain a judicial review of Appeals' decision following a CAP”, though a third party can still bring a wrongful levy suit.
Common rejections and mistakes
- Skipping the manager conference on a lien, levy or seizure appeal. Appeals returns it as premature.
- Mailing after the third business day, which lets collection resume.
- Sending Form 9423 to Appeals instead of the Collection office.
- Using CAP for an excluded issue, such as an offer rejection, a TFRP or a penalty.
- Asking Appeals to set up an alternative. CAP decides only whether the action was appropriate.
- Choosing CAP when a CDP hearing is still available, and losing court review and statute suspension.
- Thin block 15. Include the solution and the financial information Appeals will need.
Questions practitioners ask
How fast must Form 9423 be filed after the manager conference?
For lien, levy and seizure appeals, tell Collection within 2 business days after the conference and have the form received or postmarked within 3 business days, or collection may resume. Installment agreement appeals have 30 calendar days.
Can CAP be used to propose an offer in compromise?
No. Under IRM 8.24.1.2, Appeals in CAP decides only whether the action under appeal was appropriate and does not negotiate alternatives. Offer rejections have their own appeal procedure and are excluded from CAP.
Can the client go to court after a CAP decision?
No. The form instructions say there is no judicial review of an Appeals decision under CAP. Other remedies, such as a third party's wrongful levy suit, may still exist.
Does the IRS stop collecting during a CAP appeal?
Normally the action under appeal is stopped, unless the IRS believes collection is at risk. Levy is barred by statute during the 30-day appeal period for installment agreement rejections and terminations and during a timely appeal.
Is a manager conference required for an installment agreement appeal?
No. IRM 5.1.9.4.2 says the manager discussion is not mandatory for installment agreement appeals because of the statutory appeal right, though it is encouraged.
Can a third party use Form 9423?
Yes. A third party whose property is subject to a levy or lien can use CAP, including before levy proceeds are turned over in a wrongful levy situation.