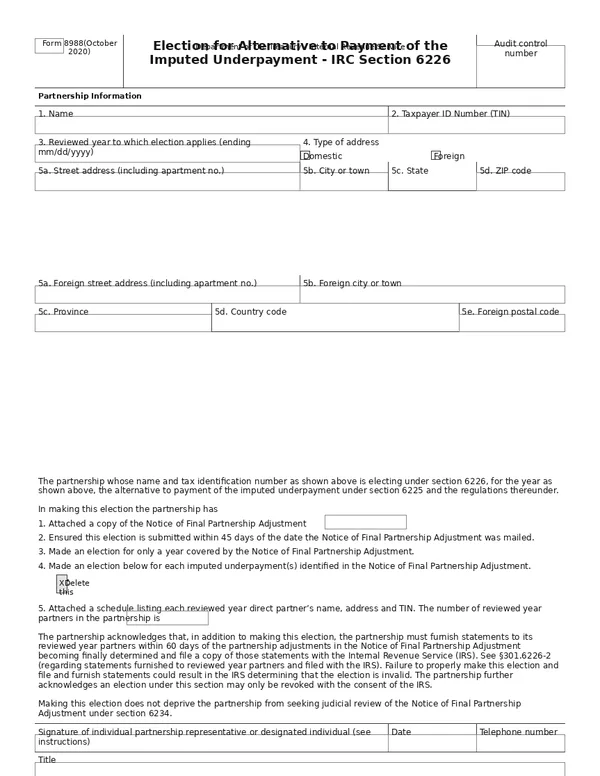
When to use Form 8988
A BBA partnership that receives a notice of final partnership adjustment (FPA) owes the imputed underpayment unless it elects the alternative under IRC 6226. The form's instructions describe the election as one to push out partnership adjustments and penalties “to its partners from the reviewed year as an alternative to payment of the imputed underpayment,” and say it “may only be made after the Notice of Final Partnership Adjustment (FPA) is mailed to the partnership.” For the decision itself (cost to partners, the higher interest rate, tiered structures), see the push-out election.
Form 8988 is for audits only. A partnership pushing out adjustments from its own AAR makes the IRC 6227(b)(2) election on Form 8082 item C1 instead.
The deadline is short and absolute. The instructions: “The election must be submitted within 45 days of the date the FPA is mailed by the IRS. The time for submitting such an election may not be extended.” Making the election does not waive the right to petition; the form states it “does not deprive the partnership from seeking judicial review” of the FPA under section 6234.
Line by line
All dates are entered as MM/DD/YYYY. The fillable form enforces character limits and will not accept double spaces or punctuation in the name field.
- ACNAudit control number
- The partnership's 10-digit audit control number from the Form 14792 provided to the partnership and PR.
- 1Name
- The partnership's full name with no double spaces or punctuation such as commas or periods. Required.
- 2Taxpayer ID Number (TIN)
- The partnership's EIN, nine digits without the dash. Required.
- 3Reviewed year to which election applies
- The ending date of the reviewed year the election covers. Required. Requirement 3 below confirms the election is only for a year covered by the FPA.
- 4Type of address
- Domestic or foreign. Required.
- 5a to 5eAddress
- Street, city, state and ZIP (5 or 9 digits) for a domestic address; foreign street, city, province, country code and postal code for a foreign address. All fields required.
- Req. 1Copy of the FPA and its date
- Attach the FPA and enter its date. The election is made only for a year covered by the FPA (requirement 3) and within 45 days (requirement 2).
- Req. 4Type of Imputed Underpayment
- Check the general imputed underpayment, each specific imputed underpayment, or both, for which the push-out is elected. Add a row for each specific IU.
- Req. 5Schedule of reviewed year direct partners
- Attach a schedule listing each reviewed year direct partner's name, address and TIN, and enter the number of reviewed year partners.
- SignSignature of individual partnership representative or designated individual
- E-signed with the 5-digit PIN selected during the Transmitter Control Code application. Required, with date and title.
- NameName of the person signing the form
- Must match the name in the e-file application exactly; the instructions give the example that John T Smith cannot sign as John Smith.
- Entity PRName of entity partnership representative (if applicable)
- Enter the entity name if the PR is an entity. The IRS countersignature block is left for the IRS.
The acknowledgment above the signature is the part to explain to the client. By signing, the partnership acknowledges it must furnish statements to reviewed year partners “within 60 days of the partnership adjustments in the Notice of Final Partnership Adjustment becoming finally determined” and file copies with the IRS, that failure “could result in the IRS determining that the election is invalid,” and that the election “may only be revoked with the consent of the IRS.”
Where and how to submit it
IRC 6241(10) lets the IRS require electronic submission, and the form says: “Please submit Form 8988 electronically.” IRM 4.31.13.11.1 says submission is required through the BBA Online Form Submission Service (OFSS) portal.
- Register for the BBA electronic submission process and obtain the PR's Transmitter Control Code and self-selected PIN well before the FPA arrives (IRS.gov/bbapartnerships).
- Download the current fillable Form 8988; the instructions warn earlier versions will be rejected, and the uploaded file must be the completed fillable form, not a scan.
- Assemble the FPA copy and the partner schedule, and name attachment files with unique names without spaces or special characters.
- If the PR or DI has changed, attach Form 8979 to the election; the Form 8985 instructions direct that.
- Submit within 45 days of the FPA mailing date and keep the receipt.
What the IRS does with it
BBA Operations reviews the election before countersigning. IRM 4.31.13.11.1 says Form 8988 “must be submitted by the AP within 45 days of issuance of the FPA,” and tells the reviewer to decide within 5 business days whether it is valid, including checking that the partner listing is complete by matching partner names to TINs on IDRS and verifying the PR, DI or POA signature.
| Result of review | IRS action (IRM 4.31.13.11.1) |
|---|---|
| Complete, timely, no petition filed | Countersign; Letter 5931 accepting the election; suspend the case until the push-out package is due |
| Complete, with signed Form 15027 | Countersign both forms and send Letter 5931 |
| Missing or incorrect information | Contact the PR or POA to perfect the form and attachments |
| Not perfected by the deadline | Reject; Letter 5931; suspend until the 90-day petition period ends or a petition is filed |
After acceptance, the clock that matters is the push-out package. IRM 4.31.13.11 sets the due date for Forms 8985 and 8986 at 60 days from the final determination date, with another 60 days for corrections under the regulations. The final determination date is 90 days after the FPA if no petition is filed, or the final court decision date plus 90 days if one is (IRM 4.31.13.6). If the package is late or does not match the FPA adjustments, the IRS may treat the election as invalid and assess the IU against the partnership.
The push-out also costs the partners more interest. The Form 8985 instructions explain that partners compute interest from the first affected year at the underpayment rate substituting “five percentage points” for “three percentage points.”
Common mistakes
- Missing the 45 days. There is no extension and no late-election relief in the form instructions.
- Partner schedule with wrong TINs or missing partners. The IRS matches names to TINs before countersigning.
- Signer name mismatch with the TCC application, or a PIN never selected.
- Uploading a scanned or outdated form. Only the current fillable version is accepted.
- Not electing for each IU. Requirement 4 must cover each general and specific IU to be pushed out.
- No plan for the 8985/8986 package. The election is only the first step; the statements due after final determination are what make it valid.
Questions practitioners ask
Can the 45-day deadline for Form 8988 be extended?
No. The form instructions say the time for submitting the election may not be extended.
Does electing push-out give up the right to go to Tax Court?
No. Form 8988 states the election does not deprive the partnership of judicial review of the FPA under section 6234. If a petition is filed, the case goes to Appeals and the push-out package is due after the final decision (IRM 4.31.13.11.1).
Can the partnership change its mind?
Only with IRS consent. The form says the election may only be revoked with the consent of the IRS; IRM 4.31.13.13.4 covers Form 8989, the revocation request, which IRM 4.31.13.11 says is due within 60 days of the final determination date and before statements are issued.
Who signs Form 8988?
The PR, or the DI if the PR is an entity, using the PIN from the TCC application. IRM 4.31.13.11.1 also refers to verifying a POA signature.
Can the partnership push out only part of the adjustments?
The election is made for each imputed underpayment checked in requirement 4, and IRM 4.31.13.11.1 tells reviewers to record whether the push-out is full or partial.