IRS forms for practitioners
The 29 forms a representative files or reviews: authorizations, abatement and refund claims, collection statements and offers, hearing requests, statute extensions, BBA partnership forms and entity elections. Each page goes line by line, with where to file and what the IRS does with it.
No forms match that. Try fewer words, or search the whole site.
Power of Attorney and Declaration of Representative
Every line of the January 2021 Form 2848, the five essential elements the CAF unit checks, and the mistakes that get it bounced with Letter 861C.
Tax Information Authorization
What Form 8821 lets a designee see, what it does not allow, each line of the January 2021 form, and the CAF rules that decide whether it is recorded.
Claim for Refund and Request for Abatement
The December 2024 redesign of Form 843, line by line, with the refund deadlines, mailing addresses and the IRM 20.1.1 rules the IRS applies to penalty requests.
Request for Taxpayer Advocate Service Assistance (and Application for Taxpayer Assistance Order)
The June 2026 Form 911, line by line, with the TAS case acceptance criteria from IRM 13.1.7 and what happens to collection while a TAS case is open.
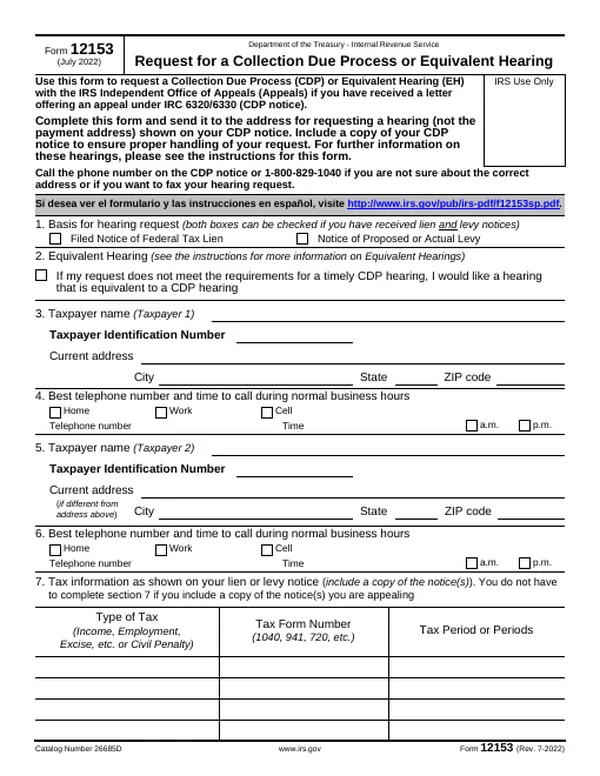
Request for a Collection Due Process or Equivalent Hearing
How to complete the July 2022 Form 12153, when a request is timely or merely processable, and what the IRM tells Collection and Appeals to do with it.
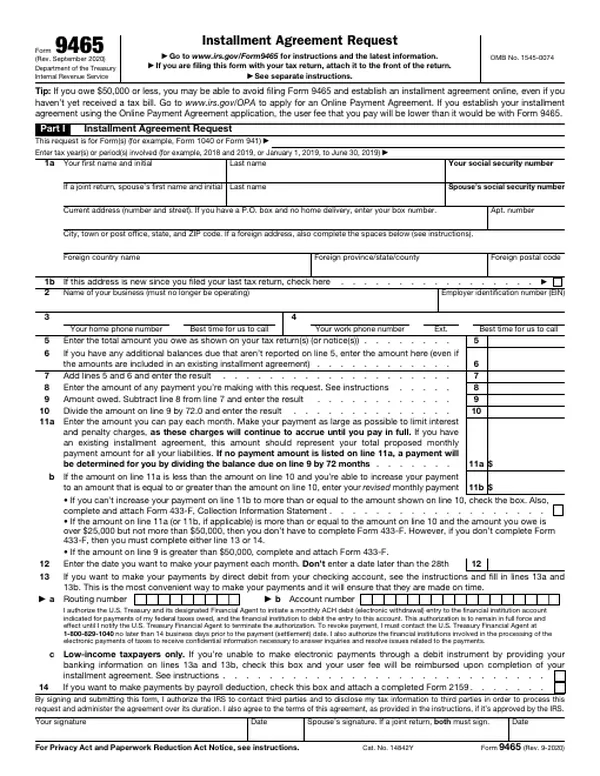
Installment Agreement Request
The September 2020 Form 9465 with its July 2024 instructions, the July 2026 IRM changes to user fees and Simple Payment Plans, and how a request becomes pending.
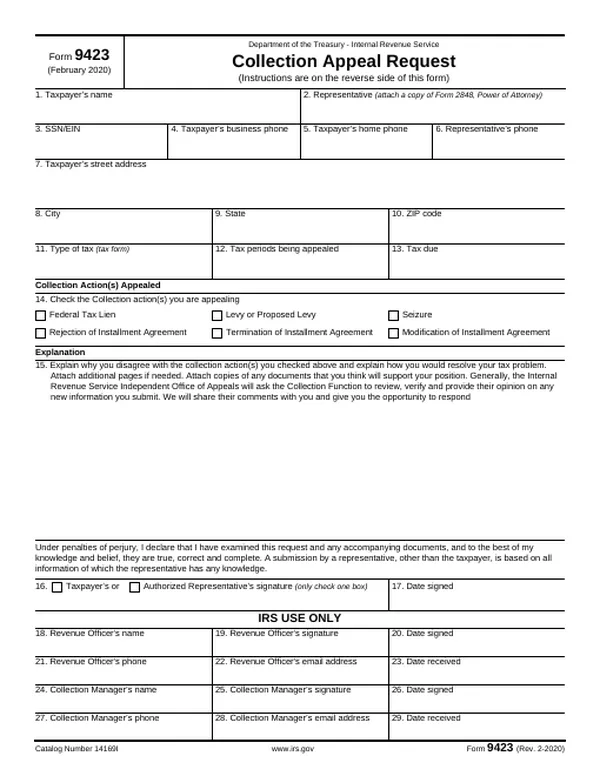
Collection Appeal Request
The February 2020 Form 9423, line by line, with the CAP rules from IRM 5.1.9.4 and IRM 8.24.1, including the business-day deadlines and what Appeals will and will not consider.
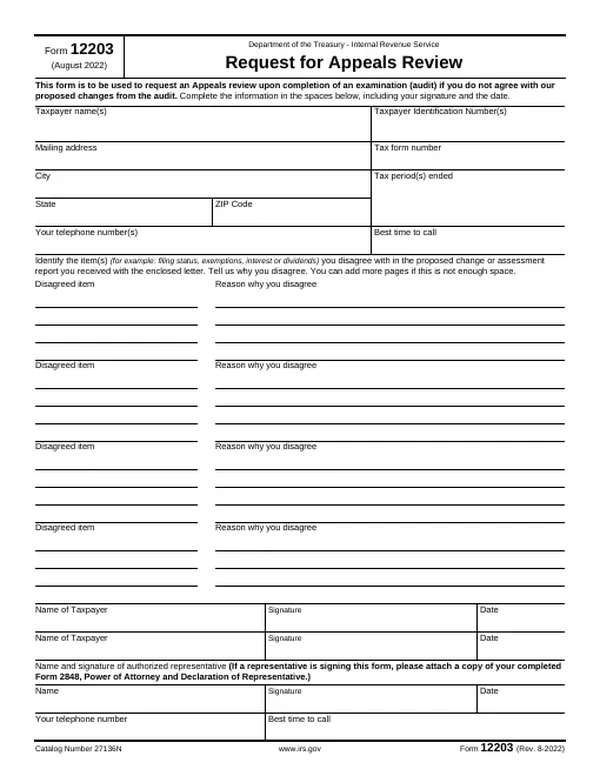
Request for Appeals Review
When Form 12203 can replace a formal protest, what each block needs, and how Appeals treats a small case under IRM 8.6.1 and Publication 5.
Request for Transcript of Tax Return
What each transcript on the April 2025 Form 4506-T shows, how to fill in each line, where it goes, and why practitioners usually pull transcripts another way.
Notice Concerning Fiduciary Relationship
The June 2026 Form 56 and instructions, line by line, with IRM 3.13.5.32 on how the IRS records a fiduciary and why a decedent's Form 2848 stops working.
Application for Extension of Time for Payment of Tax Due to Undue Hardship
When an IRC 6161 extension to pay is available, what the December 2024 Form 1127 requires, and what IRM 5.1.12.26 tells Advisory to do with it.
Request for Innocent Spouse Relief
The June 2021 Form 8857, part by part, with the filing deadlines for each type of relief and the IRM 25.15.1 rules on collection, the CSED and Tax Court review.
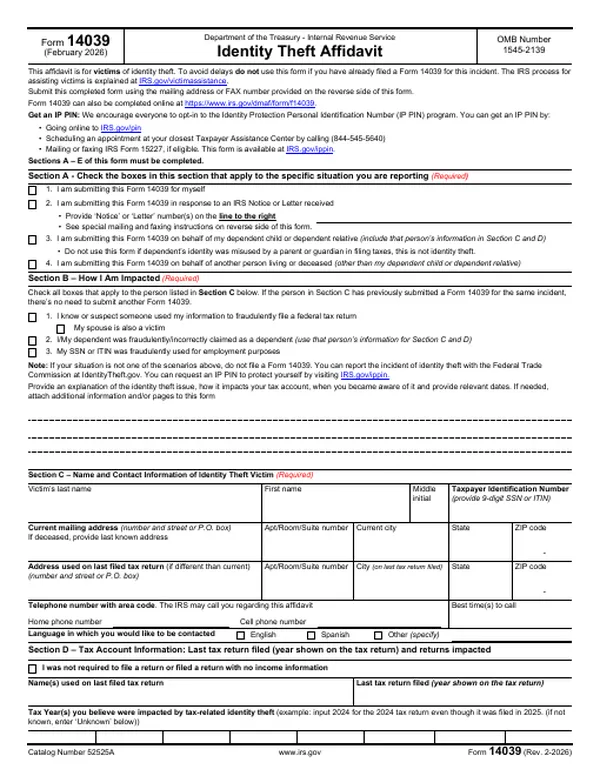
Identity Theft Affidavit
The February 2026 Form 14039, section by section, with the filing routes and how IRM 25.23 directs the Identity Theft Victim Assistance unit to treat the claim.
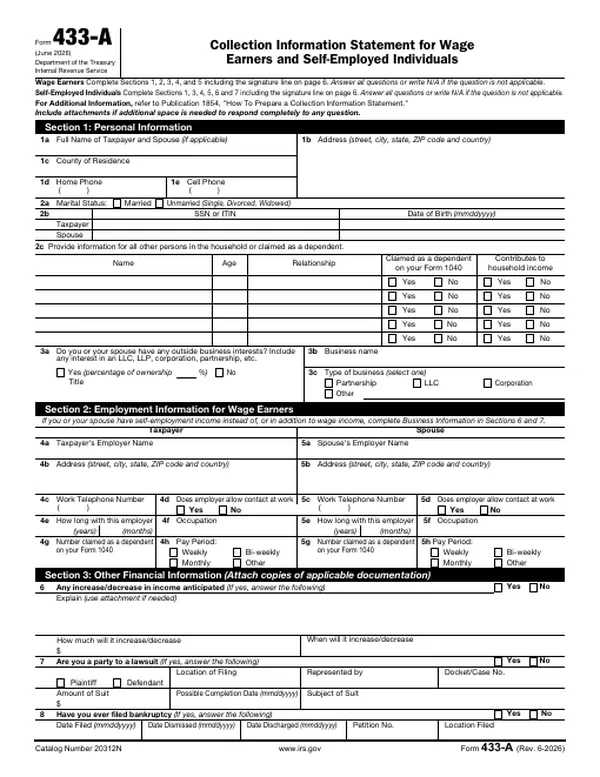
Collection Information Statement for Wage Earners and Self-Employed Individuals
The eight-page financial statement revenue officers use for individuals: what each section asks, what the IRS checks, and when a shorter or OIC version applies.
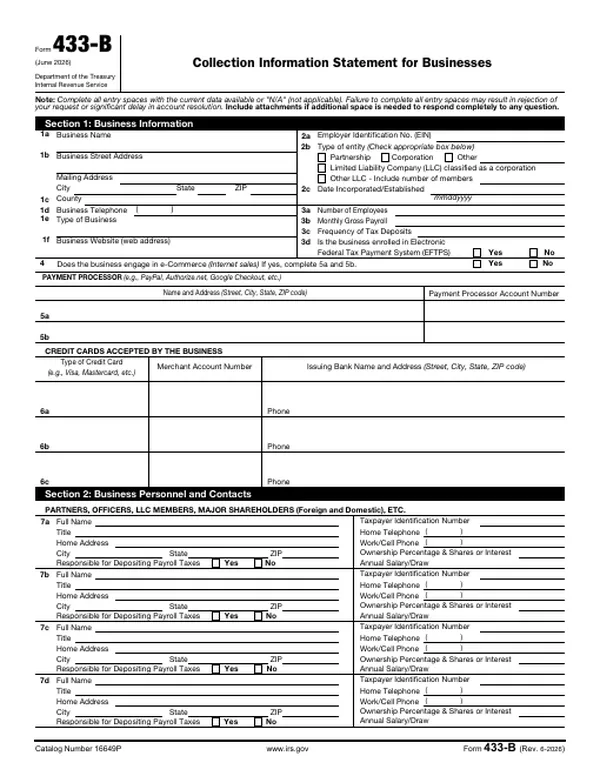
Collection Information Statement for Businesses
The business financial statement a revenue officer uses for corporations, partnerships and LLCs: each section, the IRM verification steps and the usual problems.
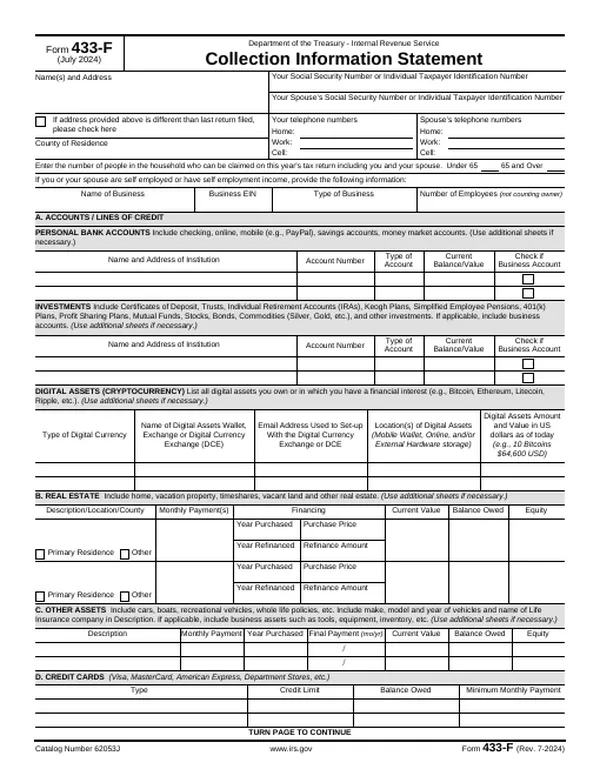
Collection Information Statement
The two-page financial statement ACS and the campuses use for individuals, when revenue officers accept it, and how each section is completed.
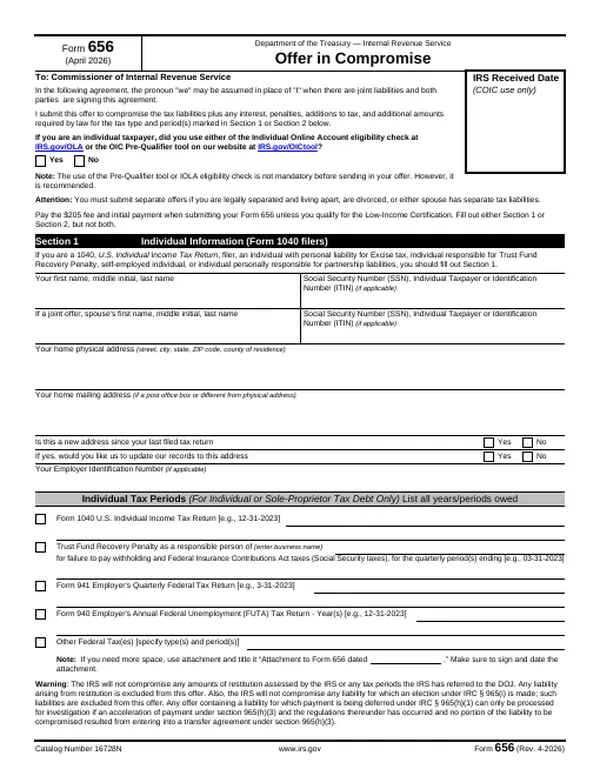
Offer in Compromise
The offer in compromise form in the April 2026 Form 656-B booklet: each section, the fee and payment rules, where to mail it and how COIC decides processability.
Consent to Extend the Time to Assess Tax
The fixed-date consent that extends the assessment statute: each element of the form, signature rules, restricted and open-ended alternatives, and the IRS procedures in IRM 25.6.22.
Waiver of Restrictions on Assessment and Collection of Deficiency in Tax and Acceptance of Overassessment
The exam waiver that lets the IRS assess an agreed deficiency: when it is used instead of Form 4549, partial agreements, interest effects and what signing gives up.
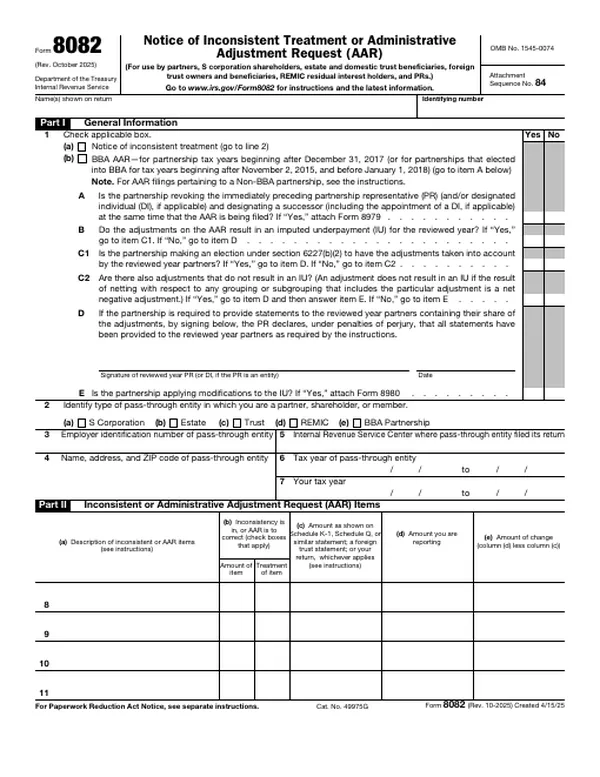
Notice of Inconsistent Treatment or Administrative Adjustment Request (AAR)
Both uses of Form 8082: a partner's or shareholder's notice of inconsistent treatment, and a BBA partnership's administrative adjustment request, line by line.
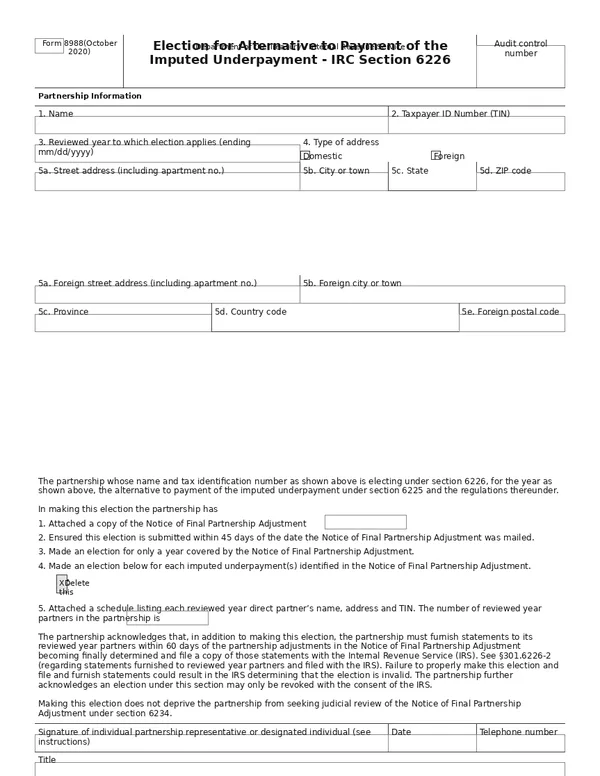
Election for Alternative to Payment of the Imputed Underpayment - IRC Section 6226
The push-out election a BBA partnership makes within 45 days of the FPA: each line, the required partner schedule, electronic submission and how BBA Operations reviews it.
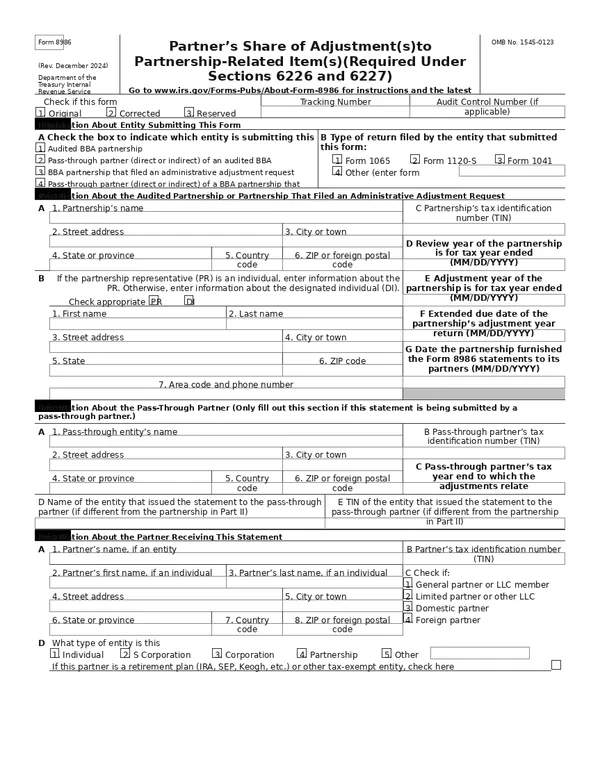
Partner's Share of Adjustment(s) to Partnership-Related Item(s) (Required Under Sections 6226 and 6227)
The statement that pushes BBA adjustments to partners: each part and column of the December 2024 revision, due dates, corrections and how recipients report it.
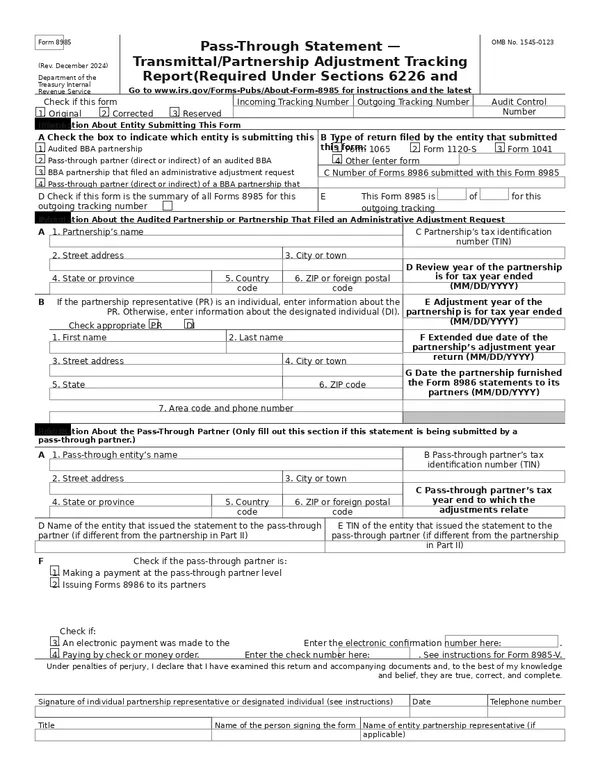
Pass-Through Statement - Transmittal/Partnership Adjustment Tracking Report (Required Under Sections 6226 and 6227)
The summary form that transmits Forms 8986 and reports pass-through partner payments: tracking numbers, signatures, due dates, and the pay-or-push decision.
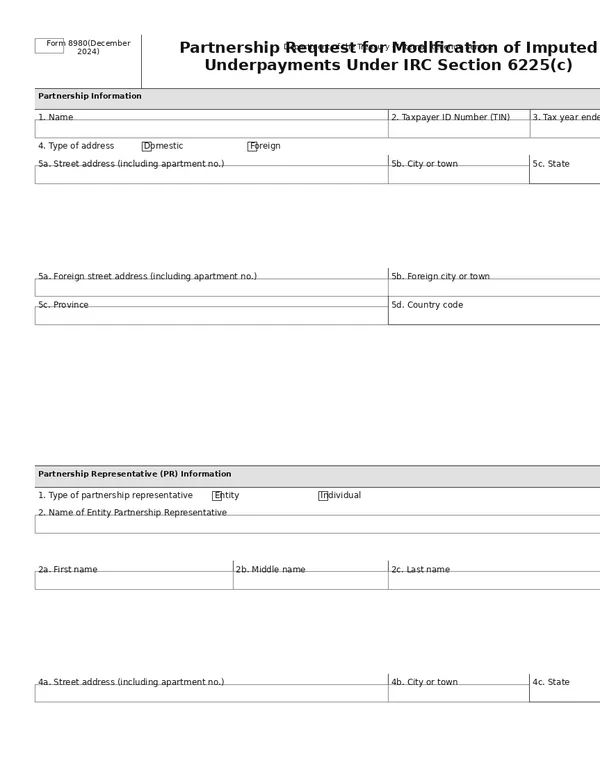
Partnership Request for Modification of Imputed Underpayments Under IRC Section 6225(c)
The request to reduce a BBA imputed underpayment: the 270-day window, each item and modification type, AAR limits, and how BBA Operations decides.
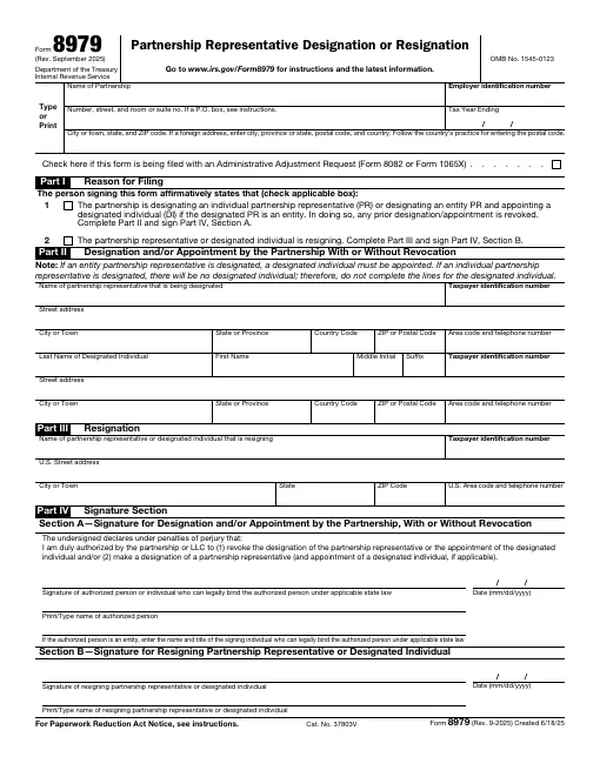
Partnership Representative Designation or Resignation
The form for designating a new partnership representative or resigning: when it can be filed, who signs, the substantial presence test and how examiners validate it.
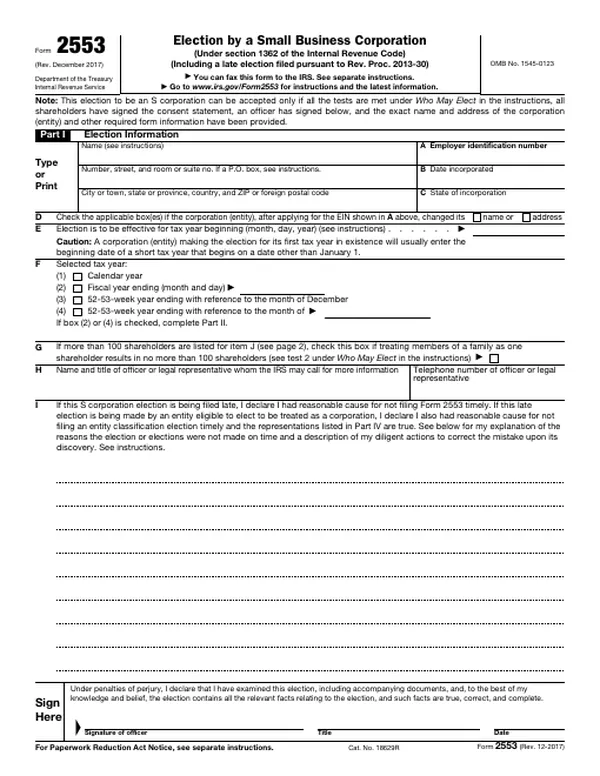
Election by a Small Business Corporation
The S corporation election: each item and part, the timing rules, where to mail or fax it, late-election relief, and how Entity processes it under IRM 3.13.2.
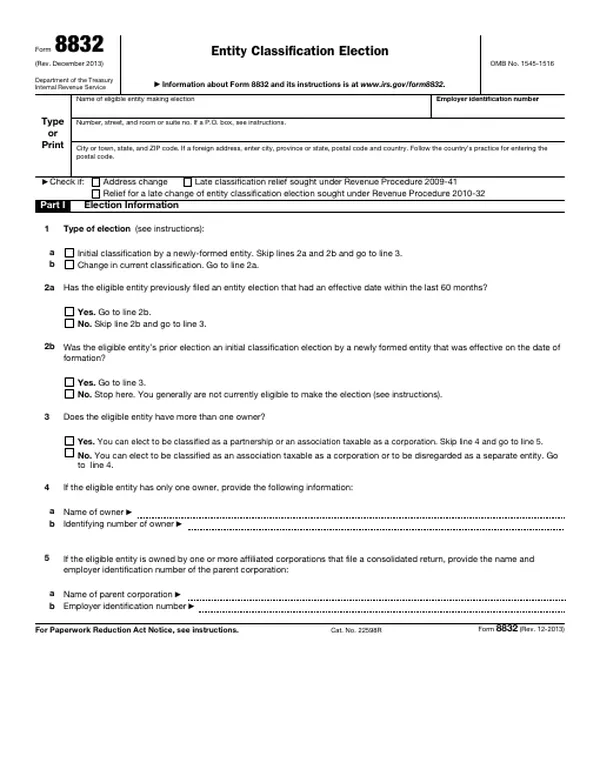
Entity Classification Election
The check-the-box election: each line, effective date limits, the 60-month rule, mailing addresses, late relief and how Entity approves or denies it.
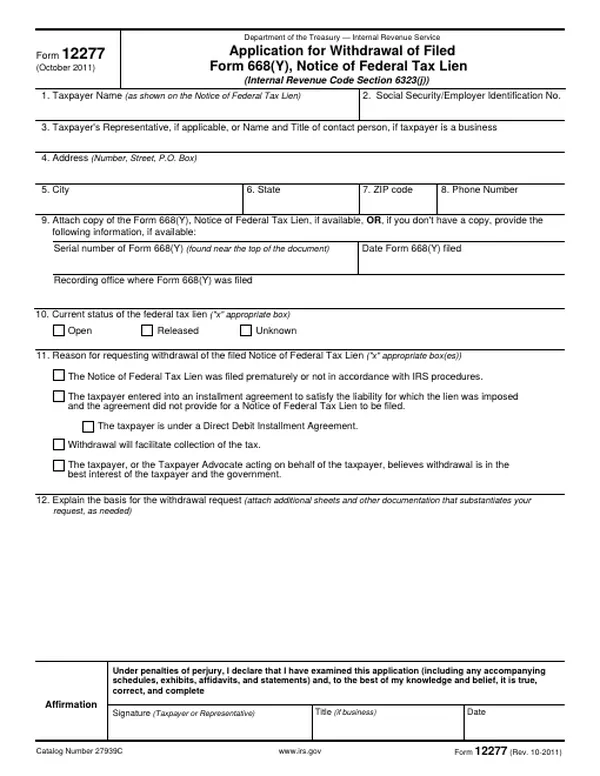
Application for Withdrawal of Filed Form 668(Y), Notice of Federal Tax Lien
The application to withdraw a filed NFTL: the four statutory grounds, the direct debit IA criteria, withdrawal after release, and how Collection Advisory decides.
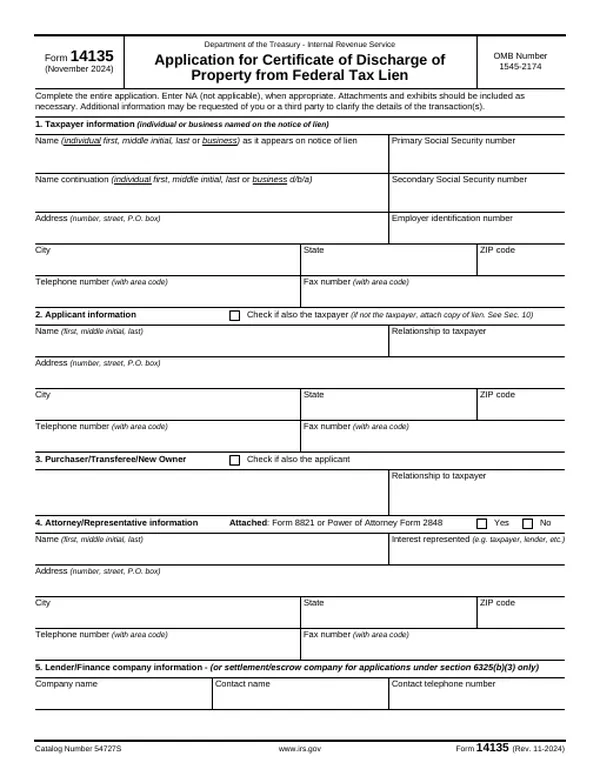
Application for Certificate of Discharge of Property from Federal Tax Lien
The application to sell or transfer property free of the federal tax lien: the IRC 6325(b) grounds, required documents, timing, payment and Advisory's review.