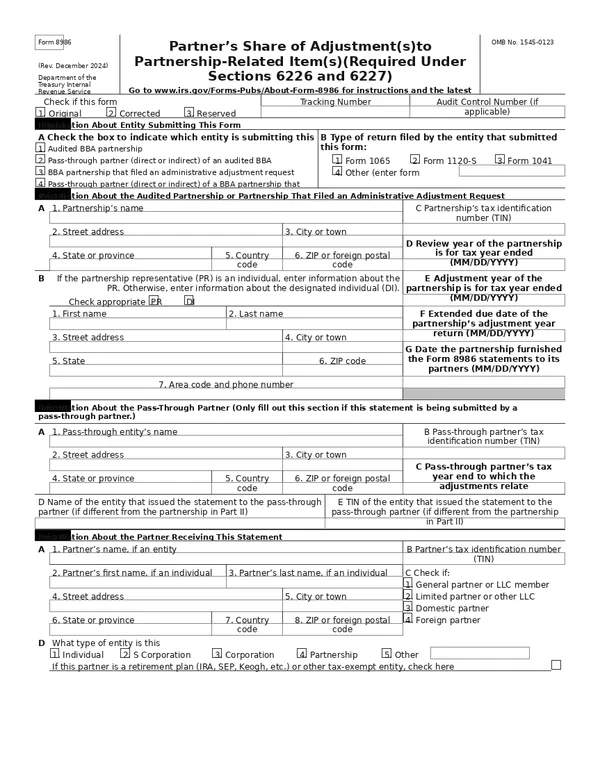
Who issues Form 8986
The instructions describe the purpose in one line: “Form 8986 is used by BBA partnerships to furnish and transmit each partner's share of adjustments to partnership-related items.” Three kinds of issuers prepare it:
- Audited partnerships that made the push-out election on Form 8988.
- Partnerships filing an AAR that either elect to push out or have adjustments that do not result in an imputed underpayment (see Form 8082).
- Direct or indirect pass-through partners that received a Form 8986 and choose to push the adjustments further, or must push out AAR adjustments that do not produce an IU.
It replaces amended K-1s in BBA corrections. The Form 8082 instructions caution: “Use Form 8986 to notify partners of their allocable shares of adjustments, don't use an amended Schedule K-1.” Each Form 8986 travels with a Form 8985 transmittal. For how the two fit together, see Forms 8985 and 8986.
Part by part
- TopOriginal, Corrected; Tracking Number; Audit Control Number
- Check original or corrected. Enter the outgoing tracking number from the related Form 8985 (required) and the audit control number from IRS correspondence; AAR filers leave the ACN blank.
- Part IInformation About Entity Submitting This Form (items A, B)
- A: whether the issuer is an audited BBA partnership, a pass-through partner of one, an AAR partnership or a pass-through partner of one (required). B: the return type the issuer files (1065, 1120-S, 1041 or other).
- Part IIInformation About the Audited Partnership or AAR Partnership (items A to G)
- Name and address exactly as on Form 8985; the PR or DI; the partnership TIN; reviewed year end (D, one Form 8986 per reviewed year); adjustment year end (E); extended due date of the adjustment year return (F, whether or not an extension was filed); and the date Forms 8986 were furnished (G).
- Part IIIInformation About the Pass-Through Partner (items A to E)
- Completed only when a pass-through partner issues the form: its name, address, TIN, the tax year end to which the adjustments relate, and the issuer of the Form 8986 it received if different from Part II.
- Part IVInformation About the Partner Receiving This Statement (items A to G)
- Name, address and TIN (required); general or limited partner and domestic or foreign; entity type (box 1 for an SSN) and tax-exempt status; profit, loss and capital percentages, liabilities and capital account, each as reported, change and corrected. For a disregarded entity partner, report the owner and list the DE in Part VI.
- Part VPartner's Total Reviewed Year Income, Gain, Loss, Deduction, Credits, and Other Items
- For each adjusted K-1 or K-3 item: (a) line number (K3 for Schedule K-3), (b) line title, (c) code or NA, (d) as reported, (e) statement in Part VI, (f) approved modifications, (g) reviewed year adjustments net of approved modifications, (h) as corrected, (d) plus (g). Increases are positive, decreases negative. Then the applicable penalties table: Code section, description, rate, line numbers and total adjustments.
- Part VIStatements
- Line number and code in column (a), detailed explanation in column (b), showing original, net change and corrected amounts. Used for section 199A detail by trade or business, K-3 detail, disguised sale descriptions, DE partner identity and other modifications not in column (f).
The December 2024 revision changed Part V. The instructions' What's New note says column headings changed and an as corrected column was added, so these columns “require different figures than the Part V columns in the previous revision of Form 8986.” Only approved amended return and closing agreement modifications belong in column (f); other modifications go in a Part VI statement.
Where, when and how to file
| Issuer | Due date | How to file (instructions) |
|---|---|---|
| Audited partnership (push-out elected) | No later than 60 days after the adjustments are finally determined | Electronically with Form 8985 (IRS.gov/BBAeSubmit) |
| Pass-through partner of an audited partnership | Extended due date of the audited partnership's adjustment year return (Part II, item F) | Electronically with Form 8985 |
| AAR partnership | With the AAR | With, and in the same manner as, the AAR, with Form 8985 |
| Pass-through partner of an AAR partnership | Extended due date of the AAR partnership's adjustment year return | Form 8985 by fax to 888-981-6982, with or without Forms 8986; packages over 100 pages are printed and mailed |
Corrections: an audited partnership or a pass-through partner of one can submit corrected Forms 8986, with a corrected Form 8985, within 60 days of the original due date without IRS permission; after that it must ask the IRS. A TIN error takes two forms: “A corrected Form 8986 with the correct TIN” and a corrected form with the incorrect TIN and zeros in Part IV, sections E through G, and Part V. Any corrected Form 8986 needs a corrected Form 8985 too.
Foreign partners create withholding obligations. The instructions say an audited partnership that furnishes a Form 8986 including an adjustment subject to chapter 3 or chapter 4 withholding must pay the withholding tax and file Form 1042 or 8804 and the related information returns for the year that includes the date Form 8986 was furnished.
What the IRS does with it
BBA Operations compares the package to the agreed or final figures. IRM 4.31.13.11.2 has the reviewer determine whether the push-out package is timely and complete, then compare the adjustments on Form 15027, Form 8985 Part IV and the Forms 8986 Part V. A timely package with no discrepancies closes as a push-out. A late package is rejected and the IU is assessed against the partnership. Where the figures do not match, the reviewer calls the PR for a corrected package and, if none arrives, revokes the push-out election by Letter 5940 and assesses the IU.
For pass-through partners, IRM 4.31.13.11.3 covers late or missing packages: the IRS assesses an IU and penalties on the pass-through partner's year that includes the audited partnership's reviewed year. The instructions say the same from the partner's side: a pass-through partner that fails to furnish and submit statements on time “may be liable for an IU as well as any penalties and interest.”
Recipients that are not pass-through partners report the adjustments on Form 8978 with their reporting year return, and may prepay to stop interest using the payment type Prepayment on BBA AAR/Exam Push Out. Partners cannot contest audit adjustments on Form 8082; see partner liability.
Common mistakes
- Using the previous revision's Part V columns. The December 2024 columns (f), (g) and (h) need different figures.
- Name or TIN in Part II not matching Form 8985. The instructions require an exact match.
- Wrong partner TIN. Fixing it takes two corrected Forms 8986 plus a corrected Form 8985.
- Entity type boxes inconsistent with the TIN. An SSN in item B means box 1, Individual.
- Disregarded entity partners reported under the DE's own TIN. Report the owner and list the DE in Part VI.
- Amounts that do not tie to Form 15027. A mismatch can lead the IRS to revoke the push-out election.
Questions practitioners ask
When is Form 8986 due after a BBA audit?
No later than 60 days after the partnership adjustments are finally determined. The final determination date is 90 days after the FPA if no petition is filed, or after the court decision becomes final (IRM 4.31.13.6; Form 8986 instructions).
Can a partner who receives Form 8986 from an audit dispute it?
Not on Form 8082. The Form 8082 instructions say partners are bound by finally determined audit adjustments on Form 8986. Inconsistent treatment is available only for Forms 8986 issued with an AAR.
What does the recipient do with Form 8986?
A partner that is not a pass-through partner reports the adjustments on Form 8978 attached to its reporting year return. A pass-through partner either pushes the adjustments further with its own Forms 8986 and 8985, or pays an IU and files Form 8985.
How do I correct a wrong TIN on a filed Form 8986?
Submit two corrected Forms 8986, one with the correct TIN and one with the incorrect TIN showing zeros in Part IV, E through G, and Part V, plus a corrected Form 8985, within the 60-day correction window or with IRS permission after it.
Do AAR partnerships file Form 8986 electronically?
They file Forms 8985 and 8986 with, and in the same manner as, the AAR. Pass-through partners of an AAR partnership fax Form 8985 to 888-981-6982.