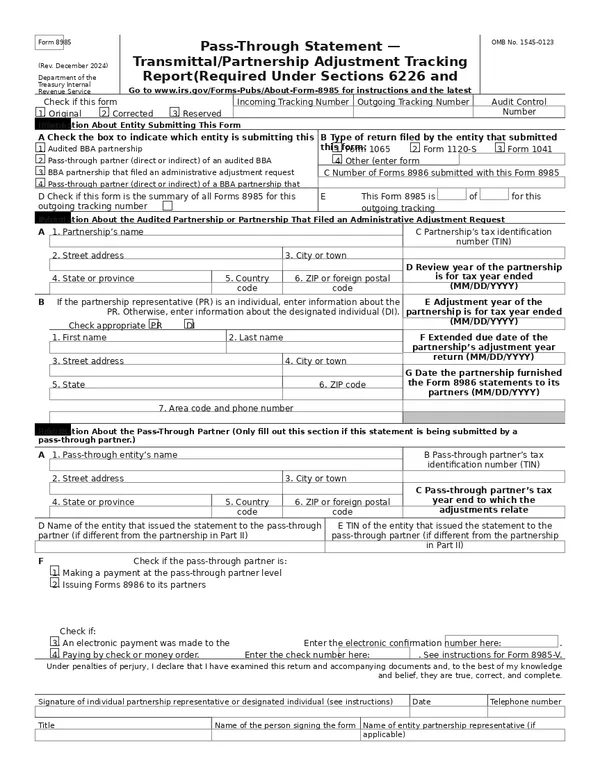
Who files Form 8985
The instructions give two purposes: Form 8985 “is used to summarize and transmit Forms 8986” by an audited partnership, AAR partnership or pass-through partner, and “is also used to report payment made and related calculations by a pass-through partner.” Filers are:
- Audited partnerships that elected push-out on Form 8988.
- Direct or indirect pass-through partners that receive a Form 8986, whether they push the adjustments further or pay instead.
- AAR partnerships that elect push-out or have adjustments that do not result in an IU (see Form 8082).
The companion Form 8986 carries each partner's share. Form 8985 is the summary, much as Schedule K-2 summarizes the Schedules K-3, which is the comparison the instructions draw.
Part by part
- TopOriginal or Corrected; Incoming and Outgoing Tracking Numbers; Audit Control Number
- A corrected Form 8985 must be submitted with all originally submitted Forms 8986, changed or not. Pass-through partners enter the incoming tracking number from the Form 8986 they received. An outgoing tracking number is needed by anyone issuing Forms 8986; audited filers obtain a unique one per push-out package, AAR filers compute it in the format YYMM1234-0000XX. The ACN does not apply to AAR filings.
- Part IInformation About Entity Submitting This Form (items A to E)
- A: type of issuer. B: return type. C: number of Forms 8986 with this Form 8985 (zero for a pass-through partner that pays instead). D and E: summary box and batch count for audited filers; generally check D and enter 1 of 1, but packages too large for one submission (the instructions discuss more than 500 partners) are batched with 1 of X, 2 of X and so on under the same tracking number.
- Part IIInformation About the Audited Partnership or the Partnership That Filed an AAR (items A to G)
- Name and address; PR (or DI if the PR is an entity) with phone; TIN; reviewed year end (one Form 8985 per reviewed year); adjustment year end; extended due date of the adjustment year return; date Forms 8986 were furnished.
- Part IIIInformation About the Pass-Through Partner Submitting This Form (items A to F)
- Name, address, TIN, tax year end to which the adjustments relate, and the issuing entity if different. Item F: box 1 to pay or box 2 to issue Forms 8986, then box 3 with the electronic payment confirmation number or box 4 with the check number, plus the tax, penalty and interest paid.
- SignSignature
- Audited or AAR partnership: the PR or DI for the reviewed year. Pass-through partner: someone authorized to sign its return, or its own PR or DI for the first affected year if it is a BBA partnership. Electronic filers e-sign with the 5-digit PIN, and the typed name must match the TCC application exactly.
- Part IVPartners' Total Reviewed Year Income, Gain, Loss, Deduction, Credits, and Other Items; Applicable Penalties
- The same columns (a) to (h) as Form 8986 Part V, totaled across all related Forms 8986 (for a pass-through partner, equal to the Form 8986 it received), plus the penalty table.
- Part VStatements
- Explanations by line and code, including the detailed IU, penalty and interest computation when a pass-through partner pays (enter Part III F in column (a)), balance sheet and capital account changes (Part IV F and Part IV G), and section 199A statements by trade or business.
A change of PR at the pass-through partner level has its own routing. If the Form 8985 relates to a BBA audit, the instructions say to fax Form 8979 separately to 888-981-6982 and include a Part V statement that the PR or DI changed and the date the Form 8979 was faxed. For an AAR, include Form 8979 with the Form 8985.
Where, when and how to file
| Filer | Due date | How |
|---|---|---|
| Audited partnership | No later than 60 days after the adjustments are finally determined | Electronically with the Forms 8986 (IRS.gov/BBAeSubmit) |
| Pass-through partner of an audited partnership | Extended due date of the audited partnership's adjustment year return (Form 8986 Part II, item F) | Electronically |
| AAR partnership | With the AAR | With, and in the same manner as, the AAR |
| Pass-through partner of an AAR partnership | Extended due date of the AAR partnership's adjustment year return | Fax to 888-981-6982, with or without Forms 8986; packages over 100 pages are printed and mailed |
A pass-through partner that pays by check or money order mails it with Form 8985-V, identified as BBA exam push out or BBA AAR push out, to Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0011, payable to United States Treasury. Electronic payments go through IRS.gov/Payments, with the confirmation number entered in Part III, item F.
Computing the payment. A paying pass-through partner computes the IU under Regulations section 301.6225-1 by treating the adjustments on the Form 8986 it received as its own adjustments for its first affected year, adds penalties determined at the partnership level, and pays interest from the due date of its first affected year return. For audit push-outs, the instructions say interest uses the section 6621(a)(2) rate “but substituting ‘five percentage points’ for ‘three percentage points.’” AAR push-outs use the regular rate. The instructions' example: $100,000 of adjustments at 37% gives a $37,000 IU, a 20% substantial understatement penalty adds $7,400, and interest at 7.5% from March 15, 2025, to April 1, 2028, adds $11,408, for $55,808 due. Pass-through partners of an AAR partnership cannot apply modifications, and AAR adjustments that do not produce an IU must still be pushed out.
What the IRS does with it
IRM 4.31.13.11 sets the audit push-out due date at 60 days from the final determination date, with an additional 60 days allowed for corrections under the regulations, and further time at IRS discretion. Under IRM 4.31.13.11.2, the reviewer checks timeliness and compares Form 15027, Form 8985 Part IV and the Forms 8986 Part V. Late packages are rejected and the IU assessed; mismatched packages are sent back for correction, and if no corrected package arrives the push-out election is revoked and the IU assessed.
For pass-through partners, IRM 4.31.13.11.3 says a Form 8985 electing to pay leads to an assessment of the IU and penalties on the pass-through partner's tax year that includes the audited partnership's reviewed year, and a late package leads to the same assessment. IRM 4.31.13.11.4 has teams start completeness checks within 60 days after the extended due date and make an IU determination under IRC 6226(b)(4) for any pass-through partner that neither pushed out nor paid. See tiered partnerships under the BBA.
Common mistakes
- Correcting Form 8985 without resubmitting every Form 8986. The instructions require all originally submitted Forms 8986 with a corrected 8985.
- Tracking number errors, especially AAR filers computing the YYMM1234-0000XX format.
- Paying without the Part V computation. A paying pass-through partner must show the IU, penalty and interest detail.
- Using the regular interest rate on an audit push-out payment. Audit push-outs add the extra percentage points.
- Pushing out only part of the adjustments. The instructions say a pass-through partner that pushes out must push out all of them.
- Signer name not matching the TCC application on electronic submissions.
Questions practitioners ask
Does a pass-through partner have to issue Forms 8986?
No. It can pay the IU instead and file Form 8985 with Part III, item F, box 1 checked and a Part V computation. Adjustments from an AAR that do not result in an IU must still be pushed out.
When is a pass-through partner's Form 8985 due?
By the extended due date of the audited (or AAR) partnership's adjustment year return, shown in Part II, item F of the Form 8986 it received.
Where does the Form 8985-V payment go?
Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0011, with a check or money order payable to United States Treasury (Instructions for Form 8985-V, December 2024).
Can a corrected Form 8985 be filed?
Yes, within 60 days of the due date of the original without permission for audit-related filings, and after that only with IRS permission. It must include all originally submitted Forms 8986.
What interest rate does a paying pass-through partner use?
For audit push-outs, the underpayment rate substituting five percentage points for three, compounded daily from the first affected year return due date. For AAR push-outs, the regular section 6621(a)(2) rate.